



Research
DePIN 2026: Past the Hype, Into Real Revenue - Top Projects Ranked
July 2, 2026
11 mins read
DePIN isn't dead. Across 650+ active projects and 8.8 million connected devices, the sector generated over $150M in combined monthly protocol revenue in January 2026. This article breaks down what DePIN is, how it works, and which networks are building real infrastructure — ranked by revenue, not speculation.


TL;DR: Decentralized Physical Infrastructure Networks (DePIN) use blockchain token incentives to coordinate real-world hardware — compute, wireless, storage, mapping. By early 2026, the sector had 650+ active projects, 8.8 million connected devices, and top networks generating $15M–$55M in monthly protocol revenue. The hype cycle is over. What remains is infrastructure that is actually being used.
Key Takeaways
- DePIN projects collectively operate 8.8 million+ active devices as of March 2026, up from under 10 million sector-wide in mid-2023
- Top 5 DePIN networks by January 2026 monthly revenue: Aethir ($55M), Render ($38M), Helium ($24M), Hivemapper ($18M), Akash ($15M)
- Aethir reached $166M ARR with 150+ enterprise clients; Helium Mobile surpassed 120,000 paying subscribers with AT&T and T-Mobile roaming partnerships
- $744M in tracked DePIN investment deals closed between 2025 and 2026, including a $300M dedicated fund from Entrée Capital
- The sector has moved from speculative token incentives to measurable protocol revenue — the defining shift between 2024 and 2026
What Is DePIN and Why Does It Matter in 2026?
DePIN — Decentralized Physical Infrastructure Networks — is a model for building and operating physical infrastructure using blockchain-based token incentives instead of centralized corporate investment. Participants contribute real hardware (wireless hotspots, GPU compute, storage capacity, mapping dashcams) and earn token rewards proportional to verified contribution.
The model matters because it solves a coordination problem that centralized infrastructure has always struggled with: getting hardware deployed at the edge, in locations where no single company would find it economical to operate. A telecom company will not build a hotspot tower for 500 rural users. A network of token-incentivized contributors will.
By early 2026, DePIN had cleared the first real test of that thesis. The sector is not running on speculation anymore — it is running on protocol fees from paying users and enterprise clients.
The bottom line: DePIN in 2026 is not a narrative. It is a revenue-generating infrastructure sector with measurable output.
What Are the Types of DePIN Networks?
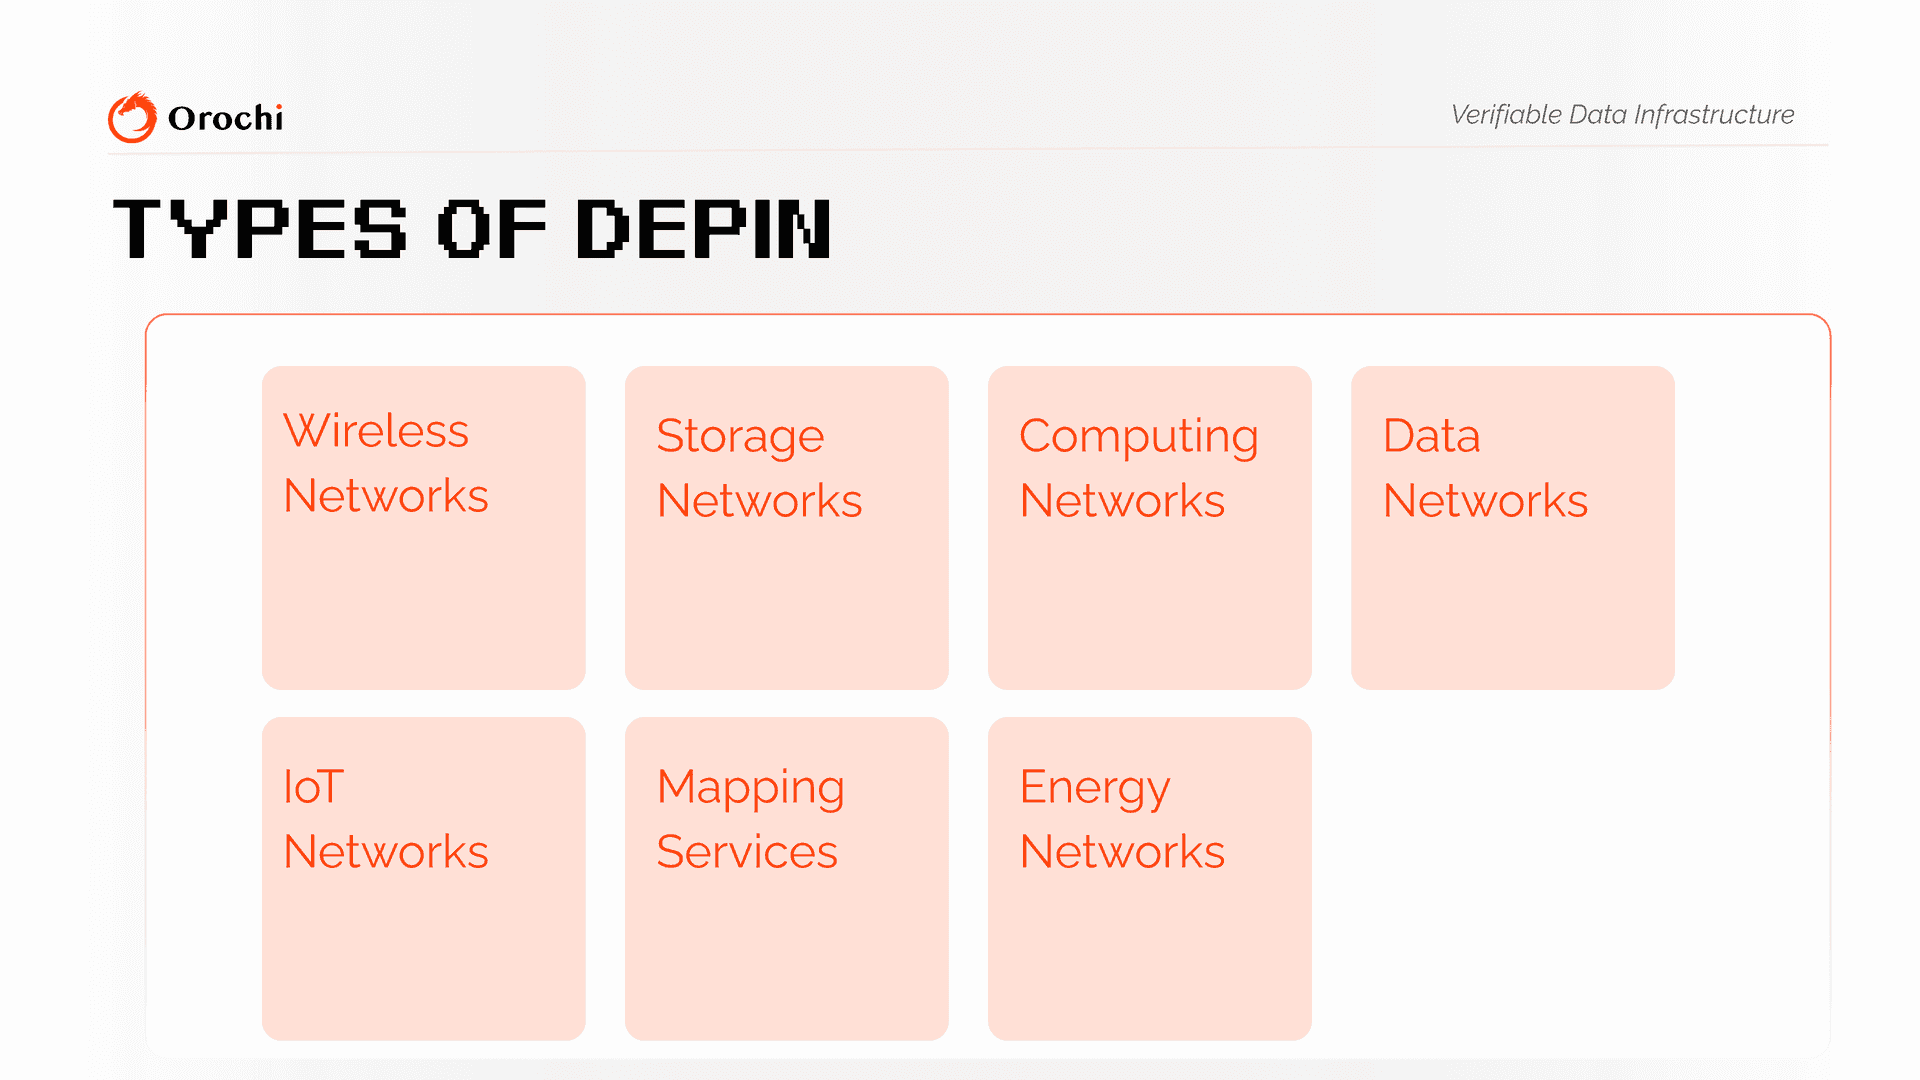
DePIN projects organize around the type of physical resource they coordinate. The categories are distinct because the hardware, incentive design, and end markets differ significantly across each.
Wireless Networks deploy hotspots and radio infrastructure to provide decentralized connectivity for IoT devices and mobile users. Helium is the canonical example, now operating 830,000 hotspots globally with carrier offload partnerships at scale.
Compute Networks aggregate idle GPU and CPU capacity from individual contributors and sell it to AI inference, rendering, and machine learning workloads. Aethir, Render, and Akash operate in this category. Render processed 68 million frames in January 2026 alone.
Storage Networks use unused disk capacity contributed by participants to provide decentralized data storage. Filecoin operates 35.2 million active storage deals with 24–41 exabytes of total data stored as of 2026.
Data and Mapping Networks pay contributors for generating proprietary datasets — Hivemapper deploys dashcams that crowdsource street-level mapping data, which it sells to autonomous vehicle companies and enterprise mapping buyers.
AI and Machine Learning Networks coordinate decentralized training and inference. Bittensor structures this through 128 active subnets running specialized AI tasks, generating $43M in Q1 2026 from real AI usage.
The bottom line: DePIN categories are defined by the physical resource being coordinated — and each category has at least one network that has demonstrated real revenue from non-speculative demand.
Where Does DePIN Stand in 2026?
The honest answer: better than the narrative suggests, more selective than the 2024 hype implied.
The sector counts 650+ distinct active projects as of March 2026, with 8.8 million active devices verified on DePINScan. Early 2026 reports put contributing devices at 13 million daily. That is not a dead sector — it is a sector that went through a shakeout and came out with fewer projects and stronger fundamentals among the survivors.
The investment signal is consistent with that reading. $744M in tracked DePIN deals closed between 2025 and 2026. Entrée Capital launched a $300M dedicated fund in December 2025 with an explicit AI agents and DePIN focus — institutional capital does not allocate at that size to dead trends.
One notable failure: Pulse, a health-wearable DePIN project, shut down independent operations in April 2026. That is what a healthy shakeout looks like — weak projects exit, capital concentrates in networks with real demand.
The bottom line: DePIN's 2024 hype cycle is over. What replaced it is a smaller set of networks generating real revenue from paying enterprise clients and end users — which is what infrastructure maturity looks like.
Which DePIN Projects Are Leading in 2026?
The following projects are ranked by January 2026 monthly protocol revenue — not price performance, not token market cap.
Aethir — $55M Monthly Revenue
Aethir operates a decentralized GPU cloud targeting AI inference, cloud gaming, and enterprise compute. As of early 2026, it serves 150+ enterprise clients across AI, gaming, and Web3 with $166M in annualized run-rate revenue and over 1.4 billion cumulative compute hours delivered. It is the highest-revenue DePIN network by protocol fees.
Render — $38M Monthly Revenue
Render aggregates GPU capacity for 3D rendering and AI inference. In January 2026, the network processed 68 million frames — a concrete output metric that maps directly to revenue. After migrating to Solana, Render expanded into AI workloads alongside its original rendering focus.
Helium — $24M Monthly Revenue
Helium operates the largest decentralized wireless network: 830,000 hotspots globally, 384,600+ active as of the post-Solana migration baseline. Helium Mobile has signed AT&T and T-Mobile for carrier offload and roaming partnerships, with 120,000+ paying mobile subscribers and cumulative paid traffic exceeding 8,500 TB. Monthly network fees reached $24M in January 2026, with $12M generated in Q1 2026.
Hivemapper — $18M Monthly Revenue
Hivemapper deploys dashcam hardware to crowdsource street-level mapping data. Revenue comes from enterprise data sales to autonomous vehicle companies — a B2B model with clear product-market fit. The network has demonstrated that DePIN can generate enterprise revenue from proprietary dataset creation, not just infrastructure usage fees.
Akash — $15M Monthly Revenue
Akash operates a decentralized compute marketplace connecting underutilized server capacity with AI and cloud workloads. The $15M monthly figure reflects actual marketplace transaction volume, not token emissions.
Bittensor — $43M Q1 2026 Revenue
Bittensor coordinates decentralized AI with 128–129 active subnets running specialized machine learning tasks. $43M in Q1 2026 revenue comes from real AI usage fees, not mining rewards. It is the most credible example of DePIN applied to AI infrastructure at scale.
Filecoin — Storage at Scale
Filecoin does not publish monthly protocol fee figures in the same format as compute networks, but the scale is evident: 35.2 million active storage deals, 24–41 exabytes stored, and 400% committed capacity growth between 2025 and 2026. Filecoin's Onchain Cloud has onboarded 100+ enterprise teams, shifting the network from speculative storage to paid enterprise infrastructure.
Source: DePINScan (March 2026), Messari, project disclosures (January 2026)
The bottom line: The top DePIN networks in 2026 are generating eight-figure monthly revenue from enterprise clients and end users. Revenue concentration has increased — the top five networks account for the majority of sector fees.
How Does DePIN Work?
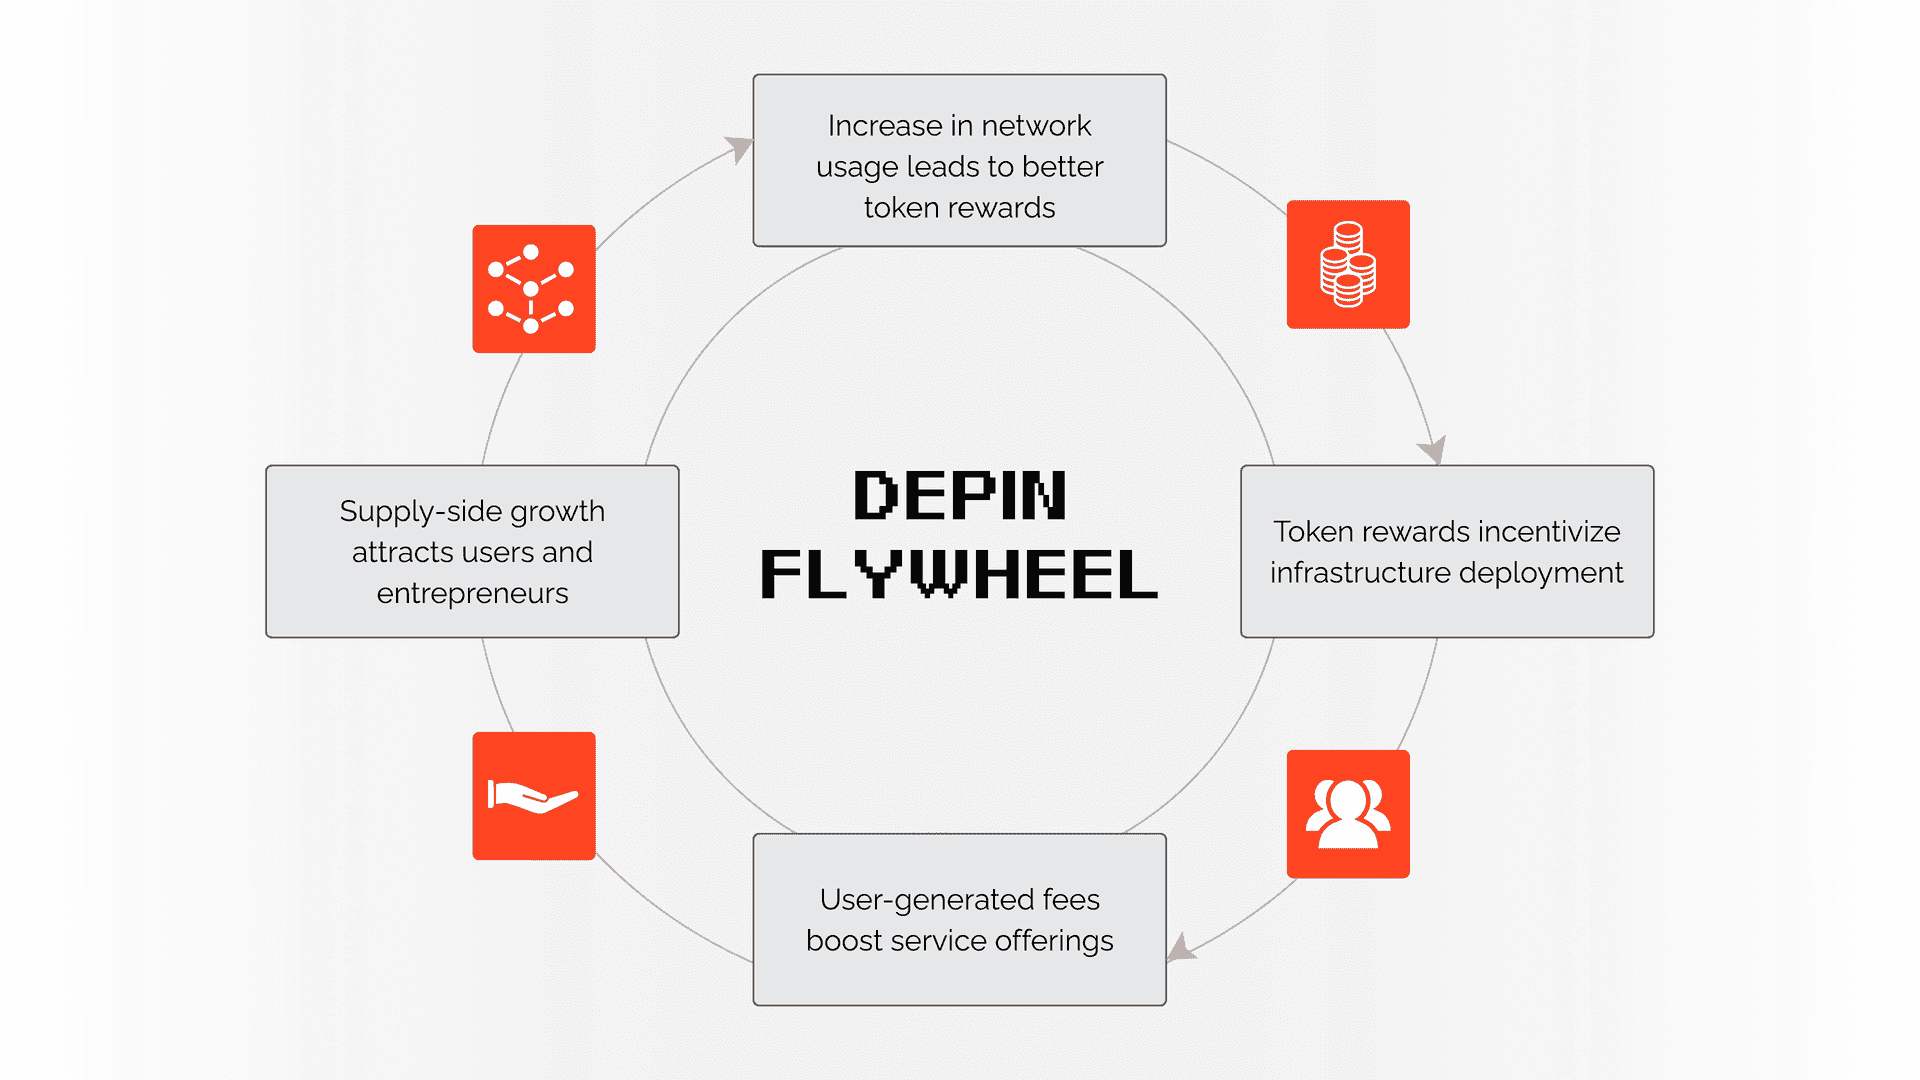
DePIN operates on an incentivized resource-sharing model enforced by blockchain. The mechanism is consistent across categories, even though the hardware differs.
Contributors deploy physical hardware — a hotspot, a GPU rig, a storage array, a dashcam — and register it with the network. The network verifies contribution using a proof mechanism specific to the resource type. Helium uses Proof-of-Coverage to verify that hotspots are providing genuine wireless coverage at the claimed location. Compute networks use cryptographic attestation to verify that GPU jobs were executed correctly.
Once contribution is verified, the network distributes token rewards and routes paying user demand to the contributor's hardware. Smart contracts handle reward distribution and service routing automatically, without a central operator.
Source: IDEASoft
The result is infrastructure that scales through individual economic incentives rather than corporate capital expenditure — and that produces verifiable output metrics (frames rendered, gigabytes stored, coverage verified) rather than self-reported attestations.
The bottom line: DePIN's mechanism converts individual hardware into a coordinated network through token incentives and on-chain proof of contribution — producing verifiable, auditable infrastructure output.
Why Does DePIN Infrastructure Matter Beyond Web3?
DePIN's relevance extends beyond crypto-native use cases. The networks that have achieved product-market fit in 2026 are selling to enterprise buyers outside the blockchain industry: autonomous vehicle companies buying Hivemapper data, AI companies buying Aethir and Render compute, mobile carriers offloading traffic to Helium.
That is the structural shift from 2024 to 2026. In 2024, DePIN revenue was primarily token-denominated rewards paid to contributors. In 2026, a meaningful share of revenue comes from external enterprise buyers paying for a service — which means the demand is independent of token speculation.
For infrastructure builders and institutional observers, this matters because it creates a new category of physical infrastructure that is verifiable by design. Every job processed by a DePIN compute network generates an on-chain record. Every coverage event on Helium is attested. Every storage deal on Filecoin is provable.
That verifiability is what separates DePIN from traditional cloud infrastructure — and it is what makes the sector relevant to anyone building systems that need auditable, tamper-evident infrastructure records.
For projects building on top of verifiable infrastructure, zkDatabase by Orochi Network provides the cryptographic layer that makes on-chain data provable end-to-end: from ingestion through storage, query, and on-chain verification using Zero-Knowledge Proofs. Where DePIN networks produce verifiable output, zkDatabase proves that output is correct and untampered.
The bottom line: DePIN's enterprise traction in 2026 demonstrates that decentralized physical infrastructure can compete on price and verifiability against centralized providers — not just in Web3, but in AI compute, wireless, and data markets.
Conclusion
DePIN in 2026 is not what the 2024 hype cycle promised, and it is not what the skeptics predicted either. It is a sector that went through a shakeout, lost the speculative projects, and emerged with a core of networks generating real revenue from paying users and enterprise clients.
The top networks by protocol revenue — Aethir at $55M monthly, Render at $38M, Helium at $24M — are not running on token emissions. They are running on demand. 650+ active projects, 8.8 million connected devices, $744M in recent investment, and a $300M dedicated fund signal that institutional capital has reached the same conclusion.
The infrastructure thesis behind DePIN — that token incentives can coordinate physical hardware at a scale and cost that centralized operators cannot match — has found its first proof points. What comes next is not hype recovery. It is infrastructure scaling.
Ready to explore verifiable infrastructure for your project?
Read how zkDatabase proves data integrity on-chain or learn about Orochi Network's Verifiable Data Infrastructure.
FAQ
What is a DePIN project and how does it generate revenue?
A DePIN (Decentralized Physical Infrastructure Network) project coordinates real-world hardware — compute, wireless, storage, mapping — through blockchain-based token incentives. Revenue is generated when external users or enterprise clients pay to use the network's services: GPU rendering jobs, wireless data offload, storage deals, or mapping data purchases. The top five DePIN networks by protocol revenue generated a combined $150M+ monthly in January 2026, primarily from non-speculative demand.
Is DePIN still relevant in 2026 or is it a dead trend?
DePIN remains active and generating measurable revenue in 2026, though the speculative phase of the cycle is over. The sector has 650+ active projects and 8.8 million connected devices as of March 2026. Networks with real enterprise demand — Aethir ($166M ARR), Helium (120,000+ mobile subscribers), Render ($38M monthly) — have demonstrated product-market fit. Projects without genuine usage have largely exited. The sector has matured from narrative to infrastructure.
Which DePIN projects have the highest revenue in 2026?
By January 2026 monthly protocol revenue: Aethir leads at $55M (GPU compute, 150+ enterprise clients), followed by Render at $38M (GPU rendering and AI inference), Helium at $24M (decentralized wireless, carrier partnerships), Hivemapper at $18M (enterprise mapping data), and Akash at $15M (decentralized compute marketplace). Bittensor generated $43M in Q1 2026 from AI subnet usage fees.
How is DePIN different from traditional cloud infrastructure?
Traditional cloud infrastructure is built and operated by centralized companies using corporate capital. DePIN coordinates individually owned hardware through token incentives, enabling infrastructure deployment at the edge where centralized operators cannot justify the cost. The key structural difference is verifiability: DePIN networks generate on-chain proof of contribution and usage — every compute job, storage deal, and coverage event is recorded and attestable. This makes DePIN infrastructure auditable by design, unlike traditional cloud.
Related toResearch




